Beating Broke

Personal Finance from the Broke Perspective

  • Home
  • About
  • We Recommend
  • Contact
  • Our Editorial Commitment

Powered by Genesis

Need Money Quick? Have a Flash Savings Challenge

November 19, 2012 By MelissaB 3 Comments

The last few months have not been kind to my family.  As Dave Ramsey says, “Murphy came to visit.”  Within the last few months, I have had several medical tests run, my computer broke so I had to buy a new one, my husband’s pay was docked $750 for two months in a row because his employer didn’t take out enough taxes, and my husband had to pay $1,700 out of pocket for a conference for work and we are waiting for reimbursement.
IOU Piggy BankBecause we were trying to pay off as much as possible as quickly as possible on our debt, we had very little in emergency savings (only about $1,000).  All of our unexpected expenses cost much more than that, so we not only used most of our emergency fund, we also added to our credit card debt.

Because we had paid down our credit card debt for 10 straight months, having to add to it for the last two months was difficult.  Even though we didn’t come close to erasing all of our progress from the last year of gazelle intensity, we definitely knew we were moving in the wrong direction.

Righting Our Situation:  A Flash Savings Challenge

My natural urge, now that everything has settled down, was to once again try to throw as much on debt as possible.  While it might have made me feel better in the short term, I realize that the next time Murphy comes to visit (and I know he’ll be back some time), we would end up in the same situation.

Instead, my husband and I decided to focus on growing our emergency fund, and quickly, before hitting the debt hard again.

Paying the minimum on our debt for the next few months so we can grow our emergency fund is almost as difficult as watching our credit card balance increase the last two months, but we both know a healthy emergency fund is necessary.  Since I am self-employed and bring in 1/3 to 1/2 of our income and work can sometimes be sporadic, we decided not to follow Dave Ramsey’s advice of a $1,000 emergency fund (because clearly that was not enough last time); instead we are aiming for $5,000.

To get started, we challenged ourselves to have $3,000 in our emergency fund by December 9th.  We started with $611 in the emergency fund, so that meant we had to come up with $2,389 in 4 weeks.

How We Are Earning $2,389 Extra in 4 Weeks

We are only one week into the challenge, but here is what we have earned so far:

  • Sold my 8 year old breast pump: $60 (Yes, it has been sitting in the basement for 7 years.  Why didn’t I sell sooner?!)
  • Sold 2 window guards to protect kids from falling:  $40
  • Listed my kids outgrown clothes on eBay:  $124 so far, but the auctions won’t end for 2 more days, so I imagine it will be more
  • 3 unexpected jobs I got as a freelancer:  $64.67
  • Turned in our change in a jar:  $62.67
  • Returned unopened vitamins I didn’t need:  $32
  • Redeemed 10,000 Swagbucks for PayPal cash:  $100

Our total so far, one week in is $483.34

Over the next few weeks, we intend to do more things to raise the additional money:

  • Put my husband’s reimbursement check in savings
  • Cash out reward points from our credit card and use them as a credit card payment.  Put the same amount in our savings since we won’t have to pay that money on the credit card
  • Put more stuff on Craigslist and eBay (We have kids’ clothes, toys, and equipment to list as well as some of my husband’s tools he hasn’t used for years.)

Why  a Flash Savings Challenge Is Working for Us

I have known that I have a lot of stuff to sell around the house, but I just never got to it.  Now, because we have set a short goal of just 4 weeks and also an ambitious goal of over $2,300 to raise, I am motivated.  Yes, listing all of this stuff is time consuming, but it is nice to get some money in the emergency fund to make us feel more secure, and I also like getting rid of our “stuff”.

If you have extra stuff around the house, especially toys and holiday clothes, now is the perfect time to sell it and make some cash.

Have you had a flash savings challenge like this?  What were your results?

img credit:Images_of_Money, on Flickr

MelissaB
MelissaB

Melissa is a writer and virtual assistant. She earned her Master’s from Southern Illinois University, and her Bachelor’s in English from the University of Michigan. When she’s not working, you can find her homeschooling her kids, reading a good book, or cooking. She resides in New York, where she loves the natural beauty of the area.
www.momsplans.com/

Filed Under: Debt Reduction, Emergency Fund, Financial Mistakes, Saving, ShareMe Tagged With: Debt Reduction, emergency fund, flash savings, frugal, Frugality, Saving

Early Morning Reality Check

March 10, 2011 By Shane Ede 13 Comments

Early yesterday morning, I awoke to my wife jumping out of bed.  “Do you smell smoke?” She asked.  Let me tell you, there are few things that will pull you out of that just woke up groggy state than a question like that.  And, sure enough, I did.  A quick check told me that there was no visible fire or smoke in the upstairs portion of our house.  It wasn’t clear what the source of the smell was.  I quickly ran downstairs to check the rest of the house, fully expecting to find a smoldering spot somewhere.  Nothing.  Down to the basement.  Nothing.  Back upstairs.  Still nothing, but the smell is still there.  I went from room to room, floor to floor, sniffing the air trying to pinpoint where the smell was strongest.  The good news was that it wasn’t getting any stronger, but I still didn’t have  source for it. The only thing that I can find is that the furnace doesn’t seem to be working.

By this point, my wife has gotten the kids up, and is working on getting them dressed just in case we have to make a hasty exit from the house.  There isn’t any immediate danger, I don’t think, but you just never know.  It just so happens that a close friend is a member of the rural fire department here.  We’re in the city fire department district, but it doesn’t hurt to ask, so we called him for some quick advice.  I quickly fill him in, and he suggests that I call the city fire department and have them come check the house for carbon monoxide and also do a hotspot check with their thermal imager.  I certainly didn’t have to be told twice, so that’s exactly what I did.

A couple firefighters show up, give the house a quick once over and come to the same conclusion that I have.  The furnace has gone out.  And, for some reason, has filled the house with the smell that we awoke to.  They can find no hot spots, and the CO tester is not indicating any CO threat.  We cut the power to the furnace, and everyone agrees that there is no immediate threat.  We can go about our business.  Well, with the exception of calling the furnace repair folks in to figure out what’s wrong with the furnace.  Some of you might not think it’s a big deal, but we still haven’t seen 30 degrees in March.  The nightly lows are in the single digits.  In just the short time that the furnace has been out, the temperature in the house has dropped 10 degrees.

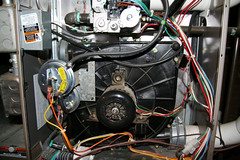
Gas Furnace Blower Motor -- IMG_9823I called the furnace repair company, and, to my surprise, they sent one out right away.  Luckily, I caught the guy as he was headed out the door for a call, so he could easily be rerouted to our house.  A couple hours later, and we had a working furnace again.  Turns out, the blower motor that pushes the air through the ductwork and into the house had stopped working.  It lost its bearings.  Literally.  The result was that it started to leak some lubricant oil and actually melted some of the electrical work in its housing which is what made the stink.  The company bills for the repair, so we only have an estimate as to what the cost of the repair will be.  The repairman thinks less than $200.

We’re lucky.  We’re lucky, because our house didn’t catch fire.  We’re lucky, because we aren’t trying to figure out how we can live out of a motel room until our fire damaged house can be repaired, or, worse, until we can find a new house to replace our destroyed house.  We’re lucky, because we aren’t trying to figure out how we’ll replace any of our belongings.  We’re lucky, because we’re safe.

But, to a lesser degree, we’re lucky, because we can afford the repair.  It wasn’t that long ago that an unexpected bill for $200 would have had us wondering if we were going to have to choose bills to go unpaid.  But, we took control of our finances.  We’ve got a long way to go, but, a $200 emergency doesn’t mean that a bill goes unpaid.  And, that makes us feel safe too.

photo credit: stevendepolo

Shane Ede

Shane Ede is a business teacher and personal finance blogger.  He holds dual Bachelors degrees in education and computer sciences, as well as a Masters Degree in educational technology.  Shane is passionate about personal finance, literacy and helping others master their money.  When he isn’t enjoying live music, Shane likes spending time with family, barbeque and meteorology.

beatingbroke.com

Filed Under: Financial Miscellaneous, General Finance, Home Tagged With: emergency, emergency fund, fire, furnace, furnace repair

Credit Cards as Emergency Funds

February 18, 2011 By Shane Ede 15 Comments

Everybody knows they need an emergency fund.  Right?  Right.  There’s some argument about how much to keep in your emergency fund, but the general rule is no less than $1000 and ideally 6-12 months of expenses.  And common savings strategies says that you should keep that money in a nice comfy savings account that you can access as needed.  But, let me play devils advocate for a minute here.  Let’s say you had $1000 in your emergency fund.  What could you do with that $1000 if it were freed up and spendable?  What if, instead of having your emergency fund in a savings account, you used a credit card that had no balance on it?

You read that right.  A credit card.

Take you’re average credit card with a $1000 to $5000 credit limit (higher if needed) and keep no balance on it.  You’ve got a ready made source of funds, up to the limit, that you can access from just about anywhere.  And, it frees up your emergency fund savings to pay down debt.  Or invest.  Or, you can still keep it in a savings if you want and just use the credit card to supplement the emergency fund so you don’t have to keep such a high balance on it.

Pros and Cons (My wife likes these lists and always makes me write one when making big decisions…)

Let’s look at the pros for using a credit card as an emergency fund.

  • Cash is freed up for investing/paying down debt.  Why earn 1% on your emergency fund cash when you could be paying off debt that you’re paying 10% or more on?  Or, that you could be investing and possibly earning a nice return on?
  • No balance needed.  The card would be dedicated to the emergency use, so you wouldn’t carry a balance on it unless you had an emergency.
  • Available anywhere.  You can instantly access your emergency fund from anywhere your card is accepted.  Which is virtually anywhere.

Now, let’s look at the cons for using a credit card as an emergency fund.

  • Card could be closed.  If you don’t carry a balance and never need it, there’s a chance that the card company could close your account and you wouldn’t be able to use it when you needed it.  There are ways around that.  You could use it for a specific bill each month and then pay it off just like you would if you were paying the bill normally.  Problems could arise if you don’t pay that balance though and fill up the card.  Then you wouldn’t be able to use it either.
  • Interest charges.  Nobody likes paying interest on anything.  If the emergency is big enough and bad enough that you aren’t able to pay it off right away, you’ll start racking up interest.  That can lead to a quick spiral into the same debt boat that you were in to begin with.  Or worse.

I don’t know if I could recommend using a credit card as your only means of an emergency fund.  But, I think you could make a pretty good argument for using one to supplement your current emergency fund.  Let’s say your goal is to have 3 months expenses in your emergency fund.  And that your expense are $5000 a month.  That’s $15000 that will just be sitting in a bank doing nothing more than earning 1% interest. If you’ve got a card with a $10000 limit on it, you could pare that down to just $5000 in the bank and use the other $10000 to pay off a bill.  Or invest in something.

I think the biggest problem with using a method like this is the potential pitfalls.  If you are unable to keep the card active and balance free, you’ll have problems using it when you need it.  If you do need it and are able to use it, but not pay it off, you could potentially end up in the deep water again.  On the other hand, if you use up a cash emergency fund, you still need to pay it off, but you won’t have to pay interest on the part you used.

Using a credit card as an emergency fund is doable.  But, I can’t suggest it for any but the most disciplined.  One wrong step, and you could end up having more of an emergency than you would have normally if you just had a cash emergency fund.  And that could lead to disaster.

What do you think?

Now, I want to know your opinion.  Would you consider using a credit card as part (or whole) of your emergency fund?  What about using a line of credit as an emergency fund source? Would higher interest rates on savings change your mind? What pros and cons did I miss?

Shane Ede

Shane Ede is a business teacher and personal finance blogger.  He holds dual Bachelors degrees in education and computer sciences, as well as a Masters Degree in educational technology.  Shane is passionate about personal finance, literacy and helping others master their money.  When he isn’t enjoying live music, Shane likes spending time with family, barbeque and meteorology.

beatingbroke.com

Filed Under: credit cards, Emergency Fund, Saving, ShareMe Tagged With: credit card, credit cards, emergency fund, Saving

  • « Previous Page
  • 1
  • …
  • 5
  • 6
  • 7
  • 8
  • 9
  • Next Page »

Improve Your Credit Score

Money Blogs

  • Budget and the Bees
  • Celebrating Financial Freedom
  • Christian PF
  • Clever Dude
  • Dual Income No Kids
  • Everybody Loves Your Money
  • Financial Panther
  • Gajizmo.com
  • Grocery Coupon Guide
  • Lazy Man and Money
  • Make Money Your Way
  • Money Talks News
  • Personal Profitability
  • PF Blogs
  • Reach Financial Independence
  • Saving Advice
  • The Savvy Scot
  • Yes, I am Cheap

Categories

Disclaimer

Please note that Beating Broke has financial relationships with some of the merchants mentioned here. Beating Broke may be compensated if consumers choose to utilize the links located throughout the content on this site and generate sales for the said merchant.

Visit Our Advertisers

Need to change careers? Consider an Accounting Certificate Program from WTI.
  • Home
  • About
  • We Recommend
  • Contact
  • Our Editorial Commitment

Subscribe to our newsletter

Please enable JavaScript in your browser to complete this form.
Loading


Beating Broke Personal Finance from the Broke Perspective

All content on Beating Broke is for entertainment purposes only. By reading this blog, you agree that Beating Broke is not responsible for any actions taken after reading this blog. For the full disclaimer.

Financial Disclaimer

Please note that Beating Broke has financial relationships with some of the merchants mentioned here. Beating Broke is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006-2026 Novara Unlimited LLC | All Rights Reserved. |
Privacy Policy | Terms of Service
Beating Broke is operated by Novara Unlimited LLC