Beating Broke

Personal Finance from the Broke Perspective

  • Home
  • About
  • We Recommend
  • Contact
  • Our Editorial Commitment

Powered by Genesis

How to Ask for a Lower Credit Card APR: What 5 Points Off Saves on $2,400

November 10, 2026 By Beating Broke Editorial Team Leave a Comment

A lower credit card APR will not erase a $2,400 balance, but at the average card rate the bank takes about $45 a month in interest before a dollar goes toward what you owe. Some of that is yours to ask back, and a few of the asks have federal rules behind them.

What $2,400 costs you at the average rate

The Federal Reserve’s G.19 consumer credit release of Nov. 6, 2026 puts the average card rate at 22.36% for commercial-bank accounts that were charged interest in the third quarter of 2026. APR (what borrowing costs you per year) is the rate on your statement, and yours may sit above or below that average.

The CFPB says many issuers figure interest every day on your average daily balance, so the meter runs all month, not only on statement day. Here is the math on $2,400 (say $2,000 you already carried plus $400 of holiday spending):

  • At 22.36%: $2,400 × 0.2236 = $536.64 a year, or $44.72 in the first month.
  • At 17.36% (five points lower): $2,400 × 0.1736 = $416.64 a year, or $34.72 in the first month.
  • The gap: $10 a month, $120 a year, on this balance.

The bigger number shows up over the whole payoff. Pay $100 a month with no new charges (our math, fixed rates). At 22.36% you are done in 33 months and pay about $811 in interest. At 17.36% you are done in 30 months and pay about $569. That is about $241 and three months back. At $75 a month, the same five points are worth about $439 (50 months and $1,285 in interest, versus 44 months and $846). A five-point cut is an example, not a promise.
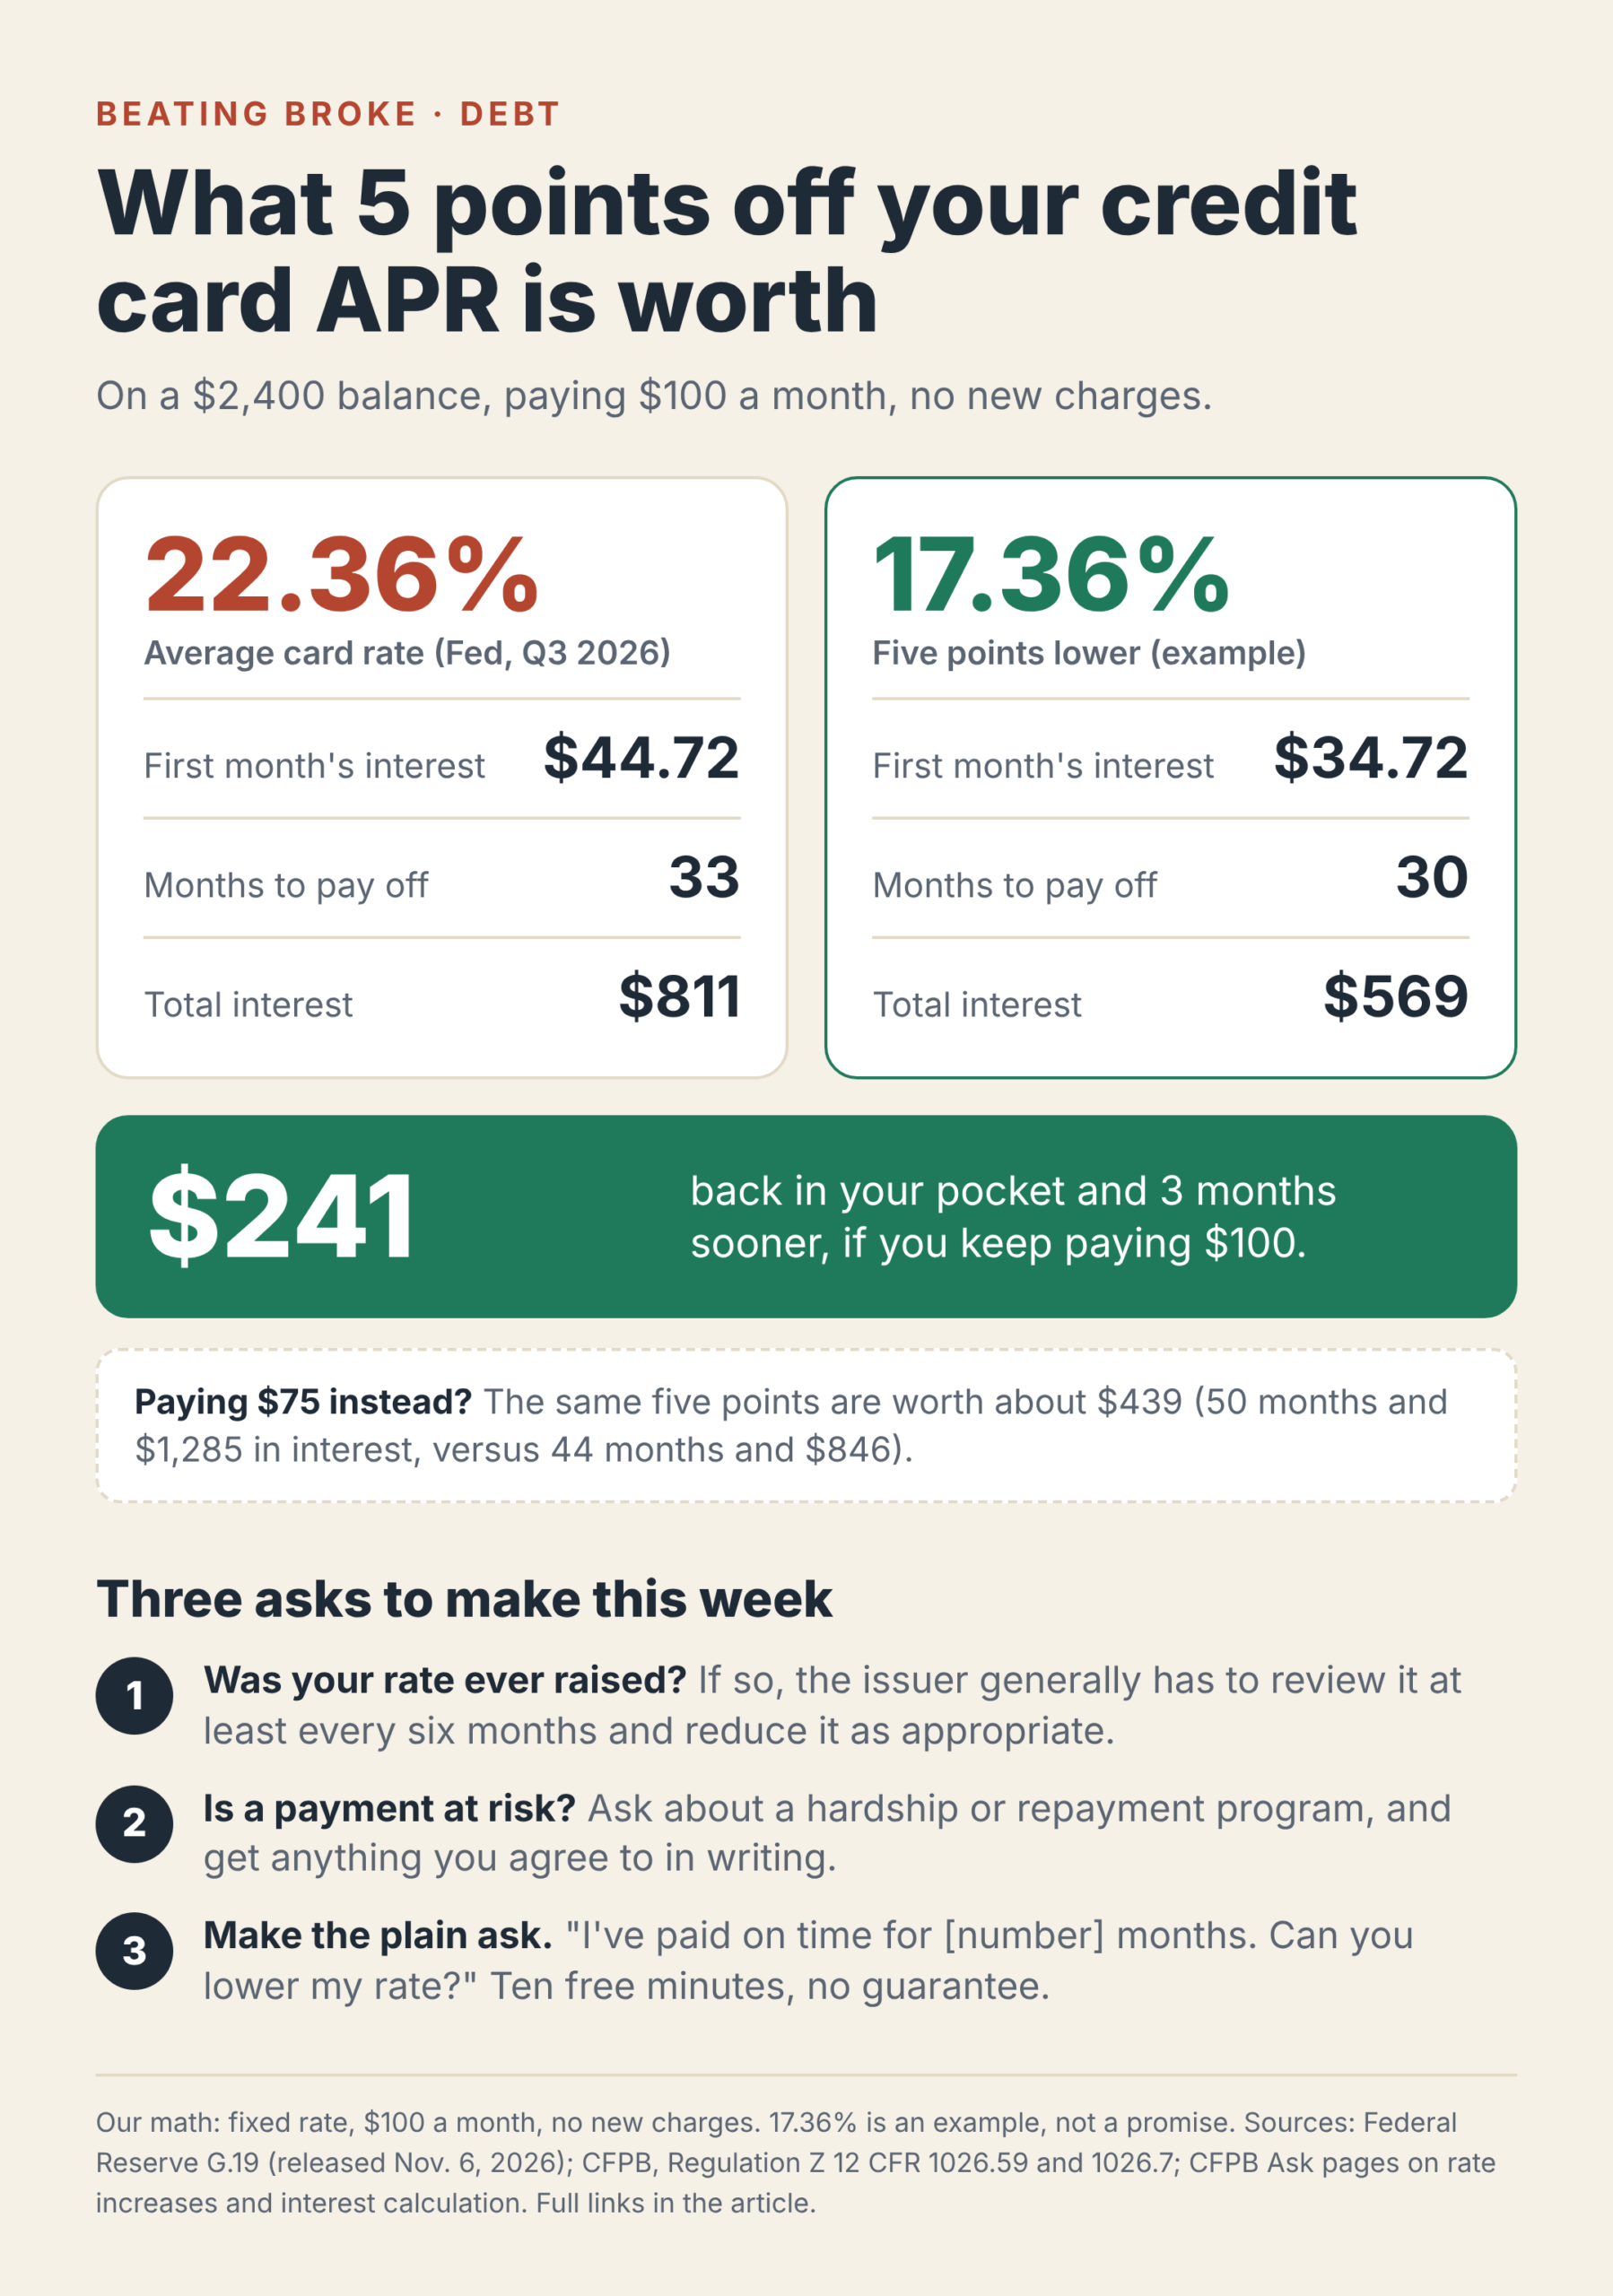
APR infographic

Read your statement first (5 minutes)

Pull your latest statement and find two things. The first is the APR on each balance; the CFPB says your statement must show each category with a different APR. The second is the minimum-payment warning box. Under Regulation Z, section 1026.7, each statement must estimate how long minimum-only payments take to clear the balance, and when that estimate runs past three years it also shows the monthly payment that would clear it in three years. Write both numbers down. They are your starting line for the call.

Three ways to get a lower credit card APR

  1. Ask whether your rate was ever raised. If the issuer raised your rate after giving 45 days of notice, the CFPB explains it generally has to review that rate at least every six months. Regulation Z, section 1026.59 says it must reduce the rate, as appropriate, within 45 days of finishing a review. The CFPB adds that if your rate is higher than a new customer would get, the issuer must reduce it, though not necessarily to your original rate. After a payment 60 days late, six straight on-time minimum payments should bring the old rate back. If your rate was never raised, this one does not apply to you; skip to number 2. Do this today: ask, “Has my rate been increased since I opened the account, and when was the last review?”
  2. Ask about a hardship or repayment program if a payment is at risk. The CFPB’s 2019 blog on calling your card company first says issuers can, and often do, offer alternative repayment options, and that these programs may let you pay a lower monthly payment at a reduced interest rate. It also says to get written confirmation of anything you agree to. Ask whether the card stays open and how the program is reported to the credit bureaus, because that page does not spell out the terms. If you are current and comfortable, skip this one.
  3. Make the plain ask. Say: “I have paid on time for [number] months, my balance is $2,400, and my rate is [your APR]. Can you lower it?” No federal rule says the answer has to be yes, and we found no federal figure on how often it works, so treat it as ten free minutes. Write down the rep’s name, the date, and whatever they offer.

Then keep your payment where it was. If the rate drops and your minimum falls with it, keep sending the $100. That is where the $241 and the three months come from.

Here’s the catch

None of these is guaranteed, and a lower rate does not shrink the balance. The savings above only show up if you hold the payment at $100; drop to $75 and you give the savings back as extra months. The hardship blog is archived content from 2019, and programs differ by issuer, so ask for the terms before you agree to anything. And if more holiday charges land on the card, run the numbers again. The ask is still worth making on a bigger balance.

What to do this week

Give it ten minutes in the next seven days. Pull the statement, write down your APR and the three-year payment, call the number on the back of the card, and ask the three questions in order. Get any new rate in writing. If it drops, keep paying $100: on $2,400, five points is worth about $241 and three months.

Sources

  1. Board of Governors of the Federal Reserve System, “Consumer Credit – G.19, September 2026”, released Nov. 6, 2026 (accessed Nov. 10, 2026)
  2. CFPB, “When can my credit card company increase my interest rate? What can I do to get the rate back down?”, last reviewed Sept. 22, 2022 (accessed Nov. 10, 2026)
  3. CFPB, “How does my credit card company calculate the amount of interest I owe?”, last reviewed Jan. 22, 2024 (accessed Nov. 10, 2026)
  4. CFPB, Regulation Z, 12 CFR 1026.59, “Reevaluation of rate increases” (accessed Nov. 10, 2026)
  5. CFPB, Regulation Z, 12 CFR 1026.7, “Periodic statement” (accessed Nov. 10, 2026)
  6. CFPB, “Need help with your credit card debt? Start with your credit card company!”, Apr. 3, 2019, archived (accessed Nov. 10, 2026)
 

Filed Under: credit cards, Debt Reduction Tagged With: credit card interest, hardship program, lower credit card APR

How to Apply for LIHEAP This Winter (Before Your State’s Heating Money Runs Out)

November 9, 2026 By Beating Broke Editorial Team Leave a Comment

If the heating bill is already behind, you are not the only one, and you are not out of options. Knowing how to apply for LIHEAP this month matters, because the 2026-27 season is opening now and the households that apply early are the ones most likely to get paid before the money runs out.

What LIHEAP actually pays for

LIHEAP (the Low Income Home Energy Assistance Program) is funded by the federal government, but you apply through your state or a local agency, not through Washington. According to the HHS Administration for Children and Families, the program can help pay home heating bills, prevent a shutoff, get service reconnected, and repair or replace heating equipment.

That last part surprises people. If the furnace died and that is why the space heater is running up the electric bill, say so when you apply.

Do you qualify? Run the number before you rule yourself out

Each state sets its own income limit. Per HHS’s LIHEAP eligibility definitions, the federal ceiling is the higher of 150% of the HHS poverty guidelines or 60% of your state’s median income, and a state can set its limit anywhere from 110% of the poverty guidelines up to that ceiling.

In real dollars, using the 2026 HHS poverty guidelines for the 48 contiguous states, 150% works out like this:

  • You and one kid: the poverty guideline is $21,640. Times 1.5, that is $32,460 a year, or about $2,705 a month before taxes.
  • You and two kids: $27,320 times 1.5 is $40,980 a year, or about $3,415 a month.

Your state’s real cutoff could be higher (if it uses the median-income option) or lower. These numbers only tell you whether the call is worth making. If you are anywhere close, make it.

Why this week beats January

There is not enough LIHEAP money for everyone who qualifies. In an October 15, 2026 release, Rep. Chris Pappas’s office reported that five of every six qualifying families get no help at all. When a state’s winter money is gone, the help stops; Oklahoma Human Services says its winter heating program closes once those funds are used up.

A long application window does not mean the money lasts that long. Pennsylvania’s Department of Human Services, for example, is taking 2026-27 applications through April 23, 2027. Apply in November anyway.

How to apply for LIHEAP in four steps

  1. Find your office (10 minutes). Go to EnergyHelp.us or call the National Energy Assistance Referral line at 1-866-674-6327, weekdays 9 a.m. to 7 p.m. Eastern, per HHS. Do this today: write down the office name and how it takes applications (online, phone, or in person).
  2. Put your papers in one folder tonight. Ask the office exactly what it needs. It is usually some version of a photo ID, Social Security numbers for everyone in the household, proof of the last 30 days of income (pay stubs or benefit letters), your most recent heating bill, and any shutoff notice. Do this today: take a phone photo of each one.
  3. Apply, and say “shutoff” out loud if it applies. If you have a disconnection notice, or your service is already off, tell the office first thing and ask whether it has a crisis or emergency track. Preventing shutoffs and reconnecting service are part of what LIHEAP pays for.
  4. Call your utility the same day. Try: “I’ve applied for LIHEAP. Can you note that on my account, and do you have a payment arrangement or hardship program?” Write down the rep’s name and the date.

Know your state’s winter shutoff rules

According to the LIHEAP Clearinghouse, 40 states and the District of Columbia have cold-weather protections that limit disconnections. Two things to know before you lean on them. First, they generally cover regulated utilities, not every energy provider, so check whether yours counts. Second, the bill keeps running: the protection delays a shutoff, but it does not lower what you owe.

So treat a winter moratorium as breathing room to get the LIHEAP application through, not as a reason to wait.

LIHEAP never charges a fee

Scammers know people are searching for heating help right now. HHS says LIHEAP does not give direct grants to individuals and does not charge a fee to receive a benefit. If a text or call offers you a “LIHEAP grant” or asks for a payment, hang up and report it to the HHS fraud hotline at 1-800-447-8477.

The catch

LIHEAP usually covers part of a winter, not all of it. You can do every step right and still hear no because your state ran out of money. That is a funding problem, not a judgment on you. If that happens, ask whether there is a waitlist, then dial 211 and ask about local energy funds, which often run separately from LIHEAP.

It also won’t touch the water bill or the rent. It is heat help. Once the heat is on and the bill is current, our budgeting pieces are where to go next.

What to do this week

Before Friday, call 1-866-674-6327 or visit EnergyHelp.us, find your local office, and get the application in. Ten minutes of calling now beats a January waitlist.

Sources

  • HHS Administration for Children and Families, “Low Income Home Energy Assistance Program (LIHEAP)” (accessed November 6, 2026)
  • HHS LIHEAP Performance Management, “LIHEAP income eligibility definitions” (accessed November 6, 2026)
  • HHS Office of the Assistant Secretary for Planning and Evaluation, “2026 Poverty Guidelines”, January 2026 (accessed November 6, 2026)
  • LIHEAP Clearinghouse (HHS), “Disconnect Policies” (accessed November 6, 2026)
  • Oklahoma Human Services, “Online enrollment period for winter heating energy assistance program opens today”, January 6, 2026 (accessed November 6, 2026)
  • Pennsylvania Department of Human Services, “Now Accepting Applications for 2026-27 LIHEAP Season” (accessed November 6, 2026)
  • Office of Rep. Chris Pappas, “Pappas Leads Bipartisan Call to Increase Home Heating Assistance Funding”, October 15, 2026 (accessed November 6, 2026)

Filed Under: budget, overdue bills Tagged With: heating assistance, how to apply for LIHEAP, utility shutoff

Seasonal Job vs. Gig Driving: What $20 an Hour Really Pays You This December

November 6, 2026 By Beating Broke Editorial Team Leave a Comment

Every December the hiring signs go up, and every one of them quotes a number that isn’t the number you take home. If you’re weighing a seasonal job vs gig driving, or a few extra hours at the job you already have, this walks the real math on all three, including the line most pay comparisons leave off: who’s watching your kid while you work.

Seasonal job vs gig driving: the number on the sign

On October 20, 2026, Amazon announced plans to hire more than 300,000 workers for the holiday season and said seasonal employees earn an average of $20 an hour. The same company also runs Flex, where drivers deliver packages as independent contractors in their own cars. So one employer is offering you two very different kinds of $20: a W-2 paycheck with taxes taken out, and a 1099 payment where everything comes out later, from you.

To compare them fairly, every example below uses the same setup:

  • You file as head of household and your income lands in the 12% federal bracket. For 2026 that bracket covers taxable income from $17,701 to $67,450 for heads of household (IRS, Rev. Proc. 2025-32).
  • Your state income tax, if your state has one, comes on top. Subtract it from every number below.
  • Childcare costs $12 an hour. That’s a stand-in. Swap in what your sitter or center actually charges.

Option 1: A W-2 seasonal shift at $20 an hour

Walk it once:

  • $20.00 gross
  • minus $1.53 for Social Security and Medicare (the 7.65% employee share, per IRS Topic 751)
  • minus $2.40 for federal income tax at 12%
  • minus about $0.34 an hour for gas (a 12-mile round trip on a five-hour shift, at 25 mpg and $3.50 a gallon, is about $1.68 a shift)

Real take-home: about $15.75 an hour.

The upside nobody puts in an ad: your employer withholds the tax, so there’s no bill waiting for you in April. The downside is that the employer sets the shift, and holiday warehouse shifts tend to land on nights and weekends, exactly when childcare is hardest to find.

Option 2: Gig driving on a 1099

Delivery pay swings by city, hour, and app, so open the app and use the offers you actually see. For the math, say a block pays $25 an hour and you drive 15 miles for every hour you work.

Start with the car. For miles driven on or after July 1, 2026, the IRS standard mileage rate is 76 cents a mile (IRS Announcement 2026-11), and the IRS sets that rate from the fixed and variable costs of running a car: gas, plus tires, oil, insurance, and the value the car loses every mile. You won’t hand all of that to a gas station each hour. A lot of it shows up later as a repair bill. It’s still real.

  • $25.00 gross
  • minus $11.40 for the car (15 miles at 76 cents)
  • = $13.60 profit
  • minus $1.92 in self-employment tax (15.3% on 92.35% of your profit, per IRS Topic 554; this is the Social Security and Medicare an employer would normally split with you)
  • minus $1.52 in federal income tax (12% of your profit after you deduct half the self-employment tax)

Real take-home: about $10.15 an hour.

Two things make or break this number. First, nobody withholds anything. Set aside about 25% of your profit, which is $3.44 of every $13.60, in a separate account the day each payout lands. Second, the mileage deduction only exists if you can prove the miles. Log every block from the first one, in the app’s tracker or a notebook in the glovebox. Without the log, you get taxed on the full $25.

Option 3: Overtime where you already work

This is the one people skip because it isn’t new, and it’s often the best paying hour on the table. Say you’re hourly at $19. Time-and-a-half is $28.50.

There’s a tax break here that’s new. Through 2028, eligible workers can deduct the extra “half” of time-and-a-half from federal income tax, up to $12,500 a year (IRS, “What to know about the No Tax on Overtime deduction”). So in this example, the $9.50 premium skips federal income tax and only the base $19 gets taxed at 12%.

  • $28.50 gross
  • minus $2.18 for Social Security and Medicare (7.65%, which still applies to the whole $28.50)
  • minus $2.28 for federal income tax (12% of the $19 base)
  • no extra commute, since you’re already there

Real take-home: about $24 an hour.

The fine print matters. The deduction only covers overtime that federal wage law requires, so it fits hourly workers and generally not salaried roles that are exempt from overtime. Starting with 2026 pay, your employer has to report the qualifying amount on your W-2 in box 12 with code TT, and if it isn’t reported there, you can’t claim it (IRS Fact Sheet 2026-13). Ask payroll now, not in February. Your paycheck still withholds as usual, so the savings show up at tax time.

The line nobody puts on the sign: childcare

Now subtract $12 for every hour someone else watches your kid:

  • Overtime: $24.00 becomes $12.00 an hour
  • W-2 seasonal shift: $15.75 becomes $3.75 an hour
  • Gig driving: $10.15 becomes minus $1.85 an hour

That’s the whole decision for a lot of single parents. A $20 sign can pay you less than four dollars an hour once there’s a sitter on the clock, and a delivery block can cost you money.

Flip it around, though, and the picture changes. The hours when childcare is free (school hours, the weekend your kid is with the other parent, the Saturday your mom already offered) are worth the full number. Gig driving at $10 an hour during school hours beats a warehouse night shift that needs a sitter. So don’t rank the jobs. Rank your hours.

What 20 free-childcare hours add up to by Christmas

Say you can find 20 hours between now and December 20 when your kid is covered at no cost:

  • 20 hours of overtime: about $480
  • 20 hours on a W-2 seasonal shift: about $315
  • 20 hours of gig driving: about $203, after you set aside the tax

That’s the number to plan around. A car repair. The gifts. Catching up the bill that slid in October. Pick the dollar target first, then count the hours it takes at your real rate.

The catch

None of these numbers include state income tax, so if your state has one, your real rate is lower. Overtime isn’t guaranteed, and on a variable schedule it can vanish the week you were counting on it. Warehouse work is physically hard and the employer controls the hours. Gig driving puts the wear on the same car you need to get to your main job, and if that car breaks down in January, the whole plan breaks with it.

One more: if you get income-based help like SNAP or a marketplace health subsidy, extra income can change what you receive. Report it when the program asks and check your new amount before you count on the extra money.

What to do this week

Get out a calendar and mark every hour between now and December 20 when your kid is covered for free. Take those hours to your manager first and ask whether overtime is available. If it isn’t, price the seasonal shift and the gig blocks with your real gas, your real miles, and your real sitter rate. If you go the gig route, open a separate savings account tonight and move 25% of every payout into it the day it hits.

Sources

  • Amazon, “Amazon holiday jobs 2026: seasonal hiring and healthcare”, October 20, 2026 (accessed November 5, 2026)
  • IRS, IR-2025-103, “IRS releases tax inflation adjustments for tax year 2026” (Rev. Proc. 2025-32), October 9, 2025 (accessed November 5, 2026)
  • IRS, Internal Revenue Bulletin 2026-29, Announcement 2026-11, “Standard Mileage Rates”, July 13, 2026 (accessed November 5, 2026)
  • IRS, Topic No. 554, “Self-employment tax” (accessed November 5, 2026)
  • IRS, Topic No. 751, “Social Security and Medicare withholding rates” (accessed November 5, 2026)
  • IRS, “What to know about the No Tax on Overtime deduction”, March 5, 2026 (accessed November 5, 2026)
  • IRS, Fact Sheet FS-2026-13, “Updates to questions and answers about the new deduction for qualified overtime compensation”, August 6, 2026 (accessed November 5, 2026)

Filed Under: career Tagged With: seasonal job vs gig driving

  • 1
  • 2
  • 3
  • …
  • 400
  • Next Page »

Improve Your Credit Score

Money Blogs

  • Budget and the Bees
  • Celebrating Financial Freedom
  • Christian PF
  • Clever Dude
  • Dual Income No Kids
  • Everybody Loves Your Money
  • Financial Panther
  • Gajizmo.com
  • Grocery Coupon Guide
  • Lazy Man and Money
  • Make Money Your Way
  • Money Talks News
  • Personal Profitability
  • PF Blogs
  • Reach Financial Independence
  • Saving Advice
  • The Savvy Scot
  • Yes, I am Cheap

Categories

Disclaimer

Please note that Beating Broke has financial relationships with some of the merchants mentioned here. Beating Broke may be compensated if consumers choose to utilize the links located throughout the content on this site and generate sales for the said merchant.

Visit Our Advertisers

Need to change careers? Consider an Accounting Certificate Program from WTI.
  • Home
  • About
  • We Recommend
  • Contact
  • Our Editorial Commitment

Subscribe to our newsletter

Please enable JavaScript in your browser to complete this form.
Loading


Beating Broke Personal Finance from the Broke Perspective

All content on Beating Broke is for entertainment purposes only. By reading this blog, you agree that Beating Broke is not responsible for any actions taken after reading this blog. For the full disclaimer.

Financial Disclaimer

Please note that Beating Broke has financial relationships with some of the merchants mentioned here. Beating Broke is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006-2026 Novara Unlimited LLC | All Rights Reserved. |
Privacy Policy | Terms of Service
Beating Broke is operated by Novara Unlimited LLC