
A lower credit card APR will not erase a $2,400 balance, but at the average card rate the bank takes about $45 a month in interest before a dollar goes toward what you owe. Some of that is yours to ask back, and a few of the asks have federal rules behind them.
What $2,400 costs you at the average rate
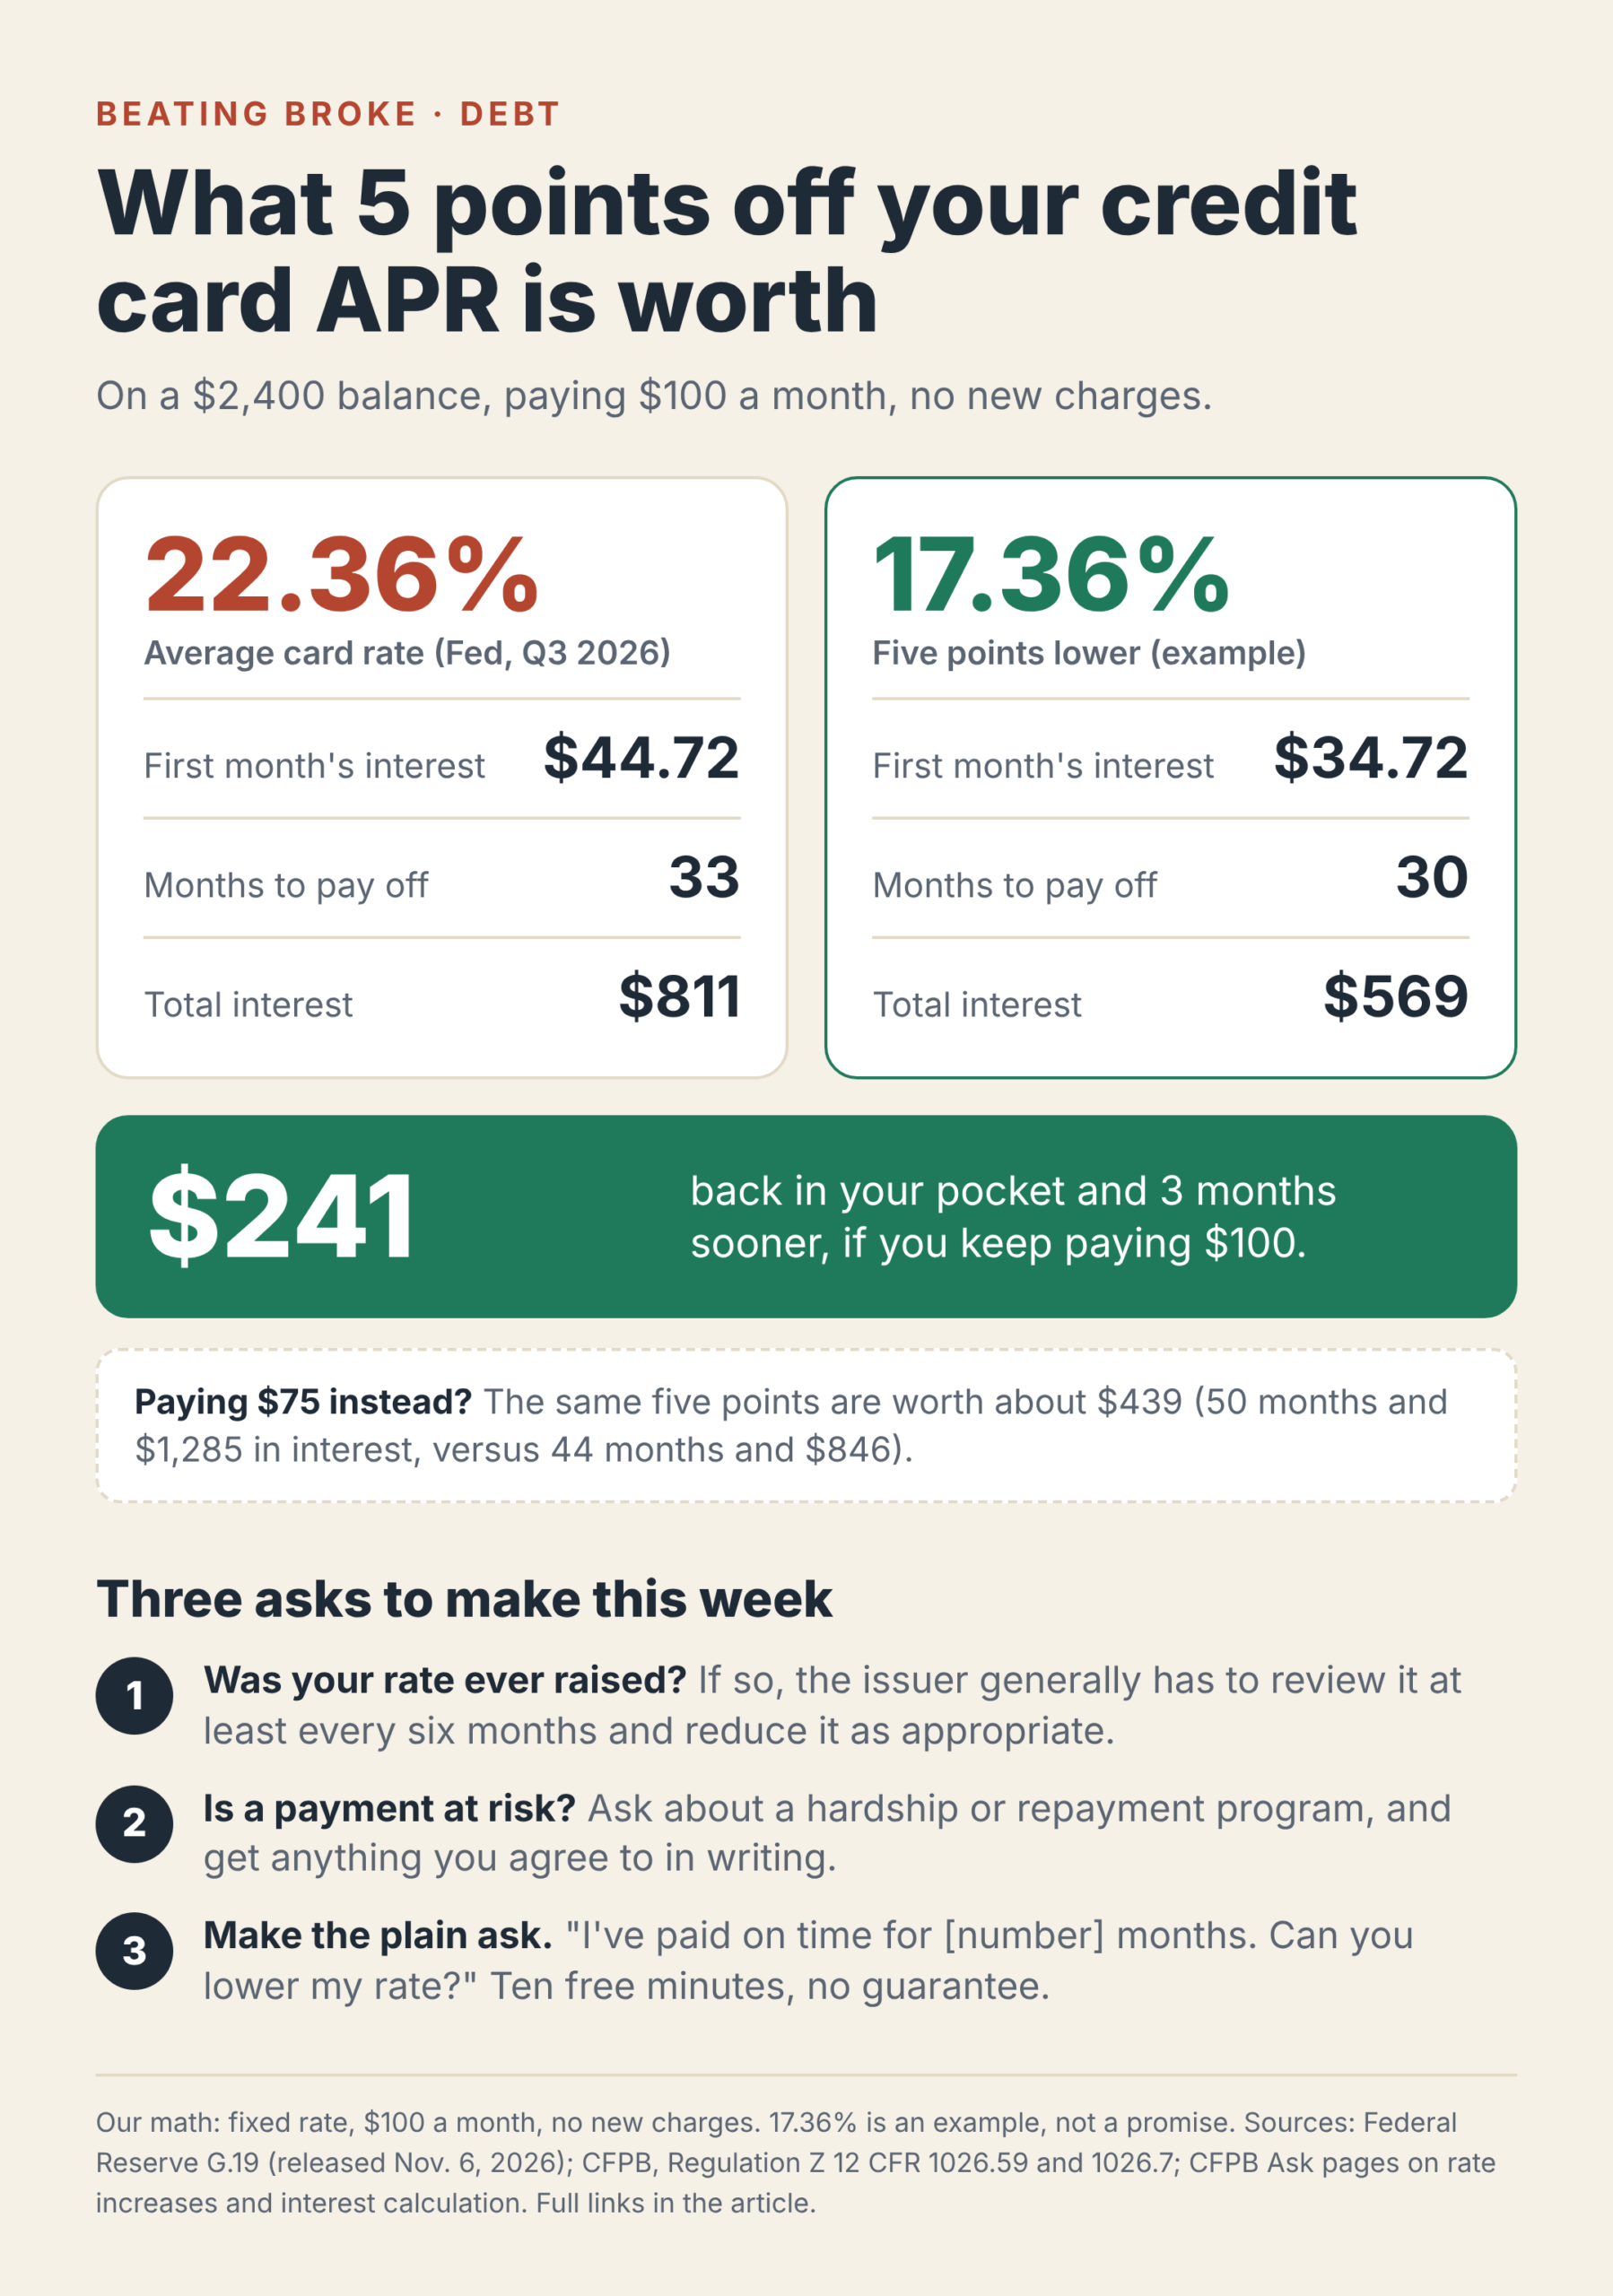
The Federal Reserve’s G.19 consumer credit release of Nov. 6, 2026 puts the average card rate at 22.36% for commercial-bank accounts that were charged interest in the third quarter of 2026. APR (what borrowing costs you per year) is the rate on your statement, and yours may sit above or below that average.
The CFPB says many issuers figure interest every day on your average daily balance, so the meter runs all month, not only on statement day. Here is the math on $2,400 (say $2,000 you already carried plus $400 of holiday spending):
- At 22.36%: $2,400 × 0.2236 = $536.64 a year, or $44.72 in the first month.
- At 17.36% (five points lower): $2,400 × 0.1736 = $416.64 a year, or $34.72 in the first month.
- The gap: $10 a month, $120 a year, on this balance.
The bigger number shows up over the whole payoff. Pay $100 a month with no new charges (our math, fixed rates). At 22.36% you are done in 33 months and pay about $811 in interest. At 17.36% you are done in 30 months and pay about $569. That is about $241 and three months back. At $75 a month, the same five points are worth about $439 (50 months and $1,285 in interest, versus 44 months and $846). A five-point cut is an example, not a promise.
Read your statement first (5 minutes)
Pull your latest statement and find two things. The first is the APR on each balance; the CFPB says your statement must show each category with a different APR. The second is the minimum-payment warning box. Under Regulation Z, section 1026.7, each statement must estimate how long minimum-only payments take to clear the balance, and when that estimate runs past three years it also shows the monthly payment that would clear it in three years. Write both numbers down. They are your starting line for the call.
Three ways to get a lower credit card APR
- Ask whether your rate was ever raised. If the issuer raised your rate after giving 45 days of notice, the CFPB explains it generally has to review that rate at least every six months. Regulation Z, section 1026.59 says it must reduce the rate, as appropriate, within 45 days of finishing a review. The CFPB adds that if your rate is higher than a new customer would get, the issuer must reduce it, though not necessarily to your original rate. After a payment 60 days late, six straight on-time minimum payments should bring the old rate back. If your rate was never raised, this one does not apply to you; skip to number 2. Do this today: ask, “Has my rate been increased since I opened the account, and when was the last review?”
- Ask about a hardship or repayment program if a payment is at risk. The CFPB’s 2019 blog on calling your card company first says issuers can, and often do, offer alternative repayment options, and that these programs may let you pay a lower monthly payment at a reduced interest rate. It also says to get written confirmation of anything you agree to. Ask whether the card stays open and how the program is reported to the credit bureaus, because that page does not spell out the terms. If you are current and comfortable, skip this one.
- Make the plain ask. Say: “I have paid on time for [number] months, my balance is $2,400, and my rate is [your APR]. Can you lower it?” No federal rule says the answer has to be yes, and we found no federal figure on how often it works, so treat it as ten free minutes. Write down the rep’s name, the date, and whatever they offer.
Then keep your payment where it was. If the rate drops and your minimum falls with it, keep sending the $100. That is where the $241 and the three months come from.
Here’s the catch
None of these is guaranteed, and a lower rate does not shrink the balance. The savings above only show up if you hold the payment at $100; drop to $75 and you give the savings back as extra months. The hardship blog is archived content from 2019, and programs differ by issuer, so ask for the terms before you agree to anything. And if more holiday charges land on the card, run the numbers again. The ask is still worth making on a bigger balance.
What to do this week
Give it ten minutes in the next seven days. Pull the statement, write down your APR and the three-year payment, call the number on the back of the card, and ask the three questions in order. Get any new rate in writing. If it drops, keep paying $100: on $2,400, five points is worth about $241 and three months.
Sources
- Board of Governors of the Federal Reserve System, “Consumer Credit – G.19, September 2026”, released Nov. 6, 2026 (accessed Nov. 10, 2026)
- CFPB, “When can my credit card company increase my interest rate? What can I do to get the rate back down?”, last reviewed Sept. 22, 2022 (accessed Nov. 10, 2026)
- CFPB, “How does my credit card company calculate the amount of interest I owe?”, last reviewed Jan. 22, 2024 (accessed Nov. 10, 2026)
- CFPB, Regulation Z, 12 CFR 1026.59, “Reevaluation of rate increases” (accessed Nov. 10, 2026)
- CFPB, Regulation Z, 12 CFR 1026.7, “Periodic statement” (accessed Nov. 10, 2026)
- CFPB, “Need help with your credit card debt? Start with your credit card company!”, Apr. 3, 2019, archived (accessed Nov. 10, 2026)
Leave a Reply