Beating Broke

Personal Finance from the Broke Perspective

  • Home
  • About
  • We Recommend
  • Contact
  • Our Editorial Commitment

Powered by Genesis

Top 5 Tips for Staying Safe at the ATM

March 21, 2011 By Shane Ede 7 Comments

We spend a lot of time talking about how to insure that our money is safely in a FDIC or NCUA insured bank or credit union.  We talk about finding the best ways to squeeze those last few pennies of interest out of our savings accounts and reduce the interest on our loans.  But, one thing we often overlook is our physical safety when it comes to money.

24hr ATMFirst, and foremost, I would like to inform you that having a swimming pool of gold coins ala McDuck is a really cool idea, but is somewhat hazardous to your health if you plan on diving into and swimming through said coins.  For those of us that can’t fill a pool full of coins (even pennies), the largest place that we need to ensure our physical and fiscal safety is while using an ATM.  Here are 5 tips to help you use the ATM as safely as possible, and protect yourself from ID theft (and physical harm).

  1. Choose a well lit ATM. Just because that ATM that’s hidden away in a dark alley is one of your in-network free ATMs, doesn’t mean you should put yourself at risk to use it.  Always choose an ATM in a well lit area.  The usage fee is worth your safety.
  2. Check for skimmers. The #1 most popular way of harming you at an ATM is the use of a skimmer.  A skimmer is a small device made to look exactly like the card reader that fits over the card reader.  As you insert your card into the reader to use the ATM, the skimmer reads the data on the card and stores it for the crooks to retrieve at a later date.  Some estimates say that these crooks have spent $250,000 on one of these devices, so they are very hard to spot.  Take a close look at the reader before you use it.  If you have any suspicions at all, report them to the staff at the institution that runs the ATM and then look for a new ATM to use temporarily.
  3. Check for cameras. Again, the crooks like to see what you’re doing when you enter your PIN.  So, they install tiny pinhole cameras that record you as you enter in your PIN and other information.  Also check for security cameras.  There’s usually one in the ATM housing itself, but having one or two in the vicinity is also a good sign.  Popular places for crooks to place pinhole cameras include the skimmer that they install, behind mirror housings, and as external stickies right out in the open.  Whatever it takes for them to be able to try and capture your PIN.  Which brings us to the next tip.
  4. Cover your PIN. When you go to enter your PIN, use your other hand or anything on hand (purse, hat, etc) to cover the PIN pad and your hand as you enter your PIN.  This little bit of caution can save you a lot of headache.
  5. Watch your back. One of the other popular ways for crooks to get your PIN is to do what is called “shoulder surf”.  Basically, as you walk up to the ATM, one of the crooks will walk up behind you and merely watch over your shoulder as you enter in you PIN.  If they can get the card, and the PIN, they can basically write their own checks from your account.  A quick glance over your shoulder or into the mirror on the ATM is usually enough to ensure someone isn’t taking a peek at your PIN

ATMs have become such a common thing in many of our everyday lives that we give very little thought to our own security while using them.  More often than not, ATMs are just as safe as going in to a branch and talking with a teller, and banks and credit unions do their best to make them ATMs as safe as possible.  Despite all of that, credit card fraud is a $1+ Billion dollar industry. Observing these 5 tips will help you avoid the risks that can sometimes occur and help you conduct your banking safely.

photo credit: ⓆiaoⒹaⓎe錫濛譙大爺

Shane Ede

Shane Ede is a business teacher and personal finance blogger.  He holds dual Bachelors degrees in education and computer sciences, as well as a Masters Degree in educational technology.  Shane is passionate about personal finance, literacy and helping others master their money.  When he isn’t enjoying live music, Shane likes spending time with family, barbeque and meteorology.
beatingbroke.com

Filed Under: credit cards, General Finance, ShareMe Tagged With: ATM, credit card fraud, credit cards, fraud, safety

Early Morning Reality Check

March 10, 2011 By Shane Ede 13 Comments

Early yesterday morning, I awoke to my wife jumping out of bed.  “Do you smell smoke?” She asked.  Let me tell you, there are few things that will pull you out of that just woke up groggy state than a question like that.  And, sure enough, I did.  A quick check told me that there was no visible fire or smoke in the upstairs portion of our house.  It wasn’t clear what the source of the smell was.  I quickly ran downstairs to check the rest of the house, fully expecting to find a smoldering spot somewhere.  Nothing.  Down to the basement.  Nothing.  Back upstairs.  Still nothing, but the smell is still there.  I went from room to room, floor to floor, sniffing the air trying to pinpoint where the smell was strongest.  The good news was that it wasn’t getting any stronger, but I still didn’t have  source for it. The only thing that I can find is that the furnace doesn’t seem to be working.

By this point, my wife has gotten the kids up, and is working on getting them dressed just in case we have to make a hasty exit from the house.  There isn’t any immediate danger, I don’t think, but you just never know.  It just so happens that a close friend is a member of the rural fire department here.  We’re in the city fire department district, but it doesn’t hurt to ask, so we called him for some quick advice.  I quickly fill him in, and he suggests that I call the city fire department and have them come check the house for carbon monoxide and also do a hotspot check with their thermal imager.  I certainly didn’t have to be told twice, so that’s exactly what I did.

A couple firefighters show up, give the house a quick once over and come to the same conclusion that I have.  The furnace has gone out.  And, for some reason, has filled the house with the smell that we awoke to.  They can find no hot spots, and the CO tester is not indicating any CO threat.  We cut the power to the furnace, and everyone agrees that there is no immediate threat.  We can go about our business.  Well, with the exception of calling the furnace repair folks in to figure out what’s wrong with the furnace.  Some of you might not think it’s a big deal, but we still haven’t seen 30 degrees in March.  The nightly lows are in the single digits.  In just the short time that the furnace has been out, the temperature in the house has dropped 10 degrees.

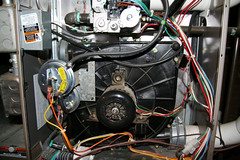
Gas Furnace Blower Motor -- IMG_9823I called the furnace repair company, and, to my surprise, they sent one out right away.  Luckily, I caught the guy as he was headed out the door for a call, so he could easily be rerouted to our house.  A couple hours later, and we had a working furnace again.  Turns out, the blower motor that pushes the air through the ductwork and into the house had stopped working.  It lost its bearings.  Literally.  The result was that it started to leak some lubricant oil and actually melted some of the electrical work in its housing which is what made the stink.  The company bills for the repair, so we only have an estimate as to what the cost of the repair will be.  The repairman thinks less than $200.

We’re lucky.  We’re lucky, because our house didn’t catch fire.  We’re lucky, because we aren’t trying to figure out how we can live out of a motel room until our fire damaged house can be repaired, or, worse, until we can find a new house to replace our destroyed house.  We’re lucky, because we aren’t trying to figure out how we’ll replace any of our belongings.  We’re lucky, because we’re safe.

But, to a lesser degree, we’re lucky, because we can afford the repair.  It wasn’t that long ago that an unexpected bill for $200 would have had us wondering if we were going to have to choose bills to go unpaid.  But, we took control of our finances.  We’ve got a long way to go, but, a $200 emergency doesn’t mean that a bill goes unpaid.  And, that makes us feel safe too.

photo credit: stevendepolo

Shane Ede

Shane Ede is a business teacher and personal finance blogger.  He holds dual Bachelors degrees in education and computer sciences, as well as a Masters Degree in educational technology.  Shane is passionate about personal finance, literacy and helping others master their money.  When he isn’t enjoying live music, Shane likes spending time with family, barbeque and meteorology.
beatingbroke.com

Filed Under: Financial Miscellaneous, General Finance, Home Tagged With: emergency, emergency fund, fire, furnace, furnace repair

Interview with Debt Free for Life Author, David Bach

February 14, 2011 By Shane Ede 4 Comments

Recently, I got the chance to review David Bachs new book, “Debt Free for Life” (Look for the review coming up on Yakezie.com!). David was kind enough to answer a few questions that I send to him. Some great stuff in there as well! Here’s the interview:

BB: Most of your previous books seem to be aimed towards people who, while likely in debt, just need a bit of a push in the right direction. Debt Free for Life, however, seems to be aimed more at people who are deep in debt and spiraling out of control. Is that what you intended? If so, what made you decide to move in that direction?

David:

For over two years I have been a weekly contributor on NBC’s Today Money 911 segment, where viewers ask me live financial questions. These questions used to be primarily focused on investment and wealth building; however, over the months I noticed that debt related questions started to dominate the segment week after week. I was also getting tons of debt questions from people on my website (www.finishrich.com ) and on my Facebook page (www.facebook.com/davidbach ). So, I decided to write Debt Free For Life as a guide intended for anyone who has debt and wants to get out—fast!

It offers an honest plan that will work—if you work it. I know some people are picking up my book because they are really drowning in debt and are looking for a life preserver. I believe this book can be the life raft that gets those people back to dry land. But let me be clear: you don’t need to be in over your head to benefit from my book. The truth is when you’re in debt; it doesn’t matter if you owe $1,000 or $100,000. I believe all debt is bad debt if you don’t have an action plan to pay if off. Debt Free For Life is about a totally new approach to building financial freedom that stresses “paying down your debt” so you can take control of your financial life. I teach my readers a revolutionary new system that makes paying off your debt easier than it ever has been—no matter how much you owe!

BB: You spend a good deal of the book talking about subjects like debt settlement, time-barred debt, and bankruptcy.  Those are topics that seem to be frowned upon by many of the mainstream personal finance folks. Were you afraid, while writing and publishing the book, that those same personal finance people would chastise you for bringing the subjects up?

David:

No, I wasn’t afraid to bring up those subjects. People should be educated about the good, the bad and the ugly of personal finances –each person’s situation is different – so it’s imperative to provide the readers with all the options, information, and tools possible so that they can make the right decision based on their own personal financial position. I think a lot of times people can get themselves into these sticky financial situations by being undereducated and misinformed about what options are available to them.

Time-barred debt, debt settlement and bankruptcy are all options that can be considered depending on your financial situation but you will need to take a very close look at your finances and you may be required to seek a professional in order to choose one of these options.  With time-barred debt, you need to consult an attorney before taking any action, but yes, I do believe that you’re entitled to use your legal rights in that regard to get out of debt and get back on your feet financially. Time barred debt is basically the equivalent of the statute of limitations in regards to your finances and debts.

As for debt settlement you can usually use the rule of thumb – if it sounds too good to be true—it probably is too good to be true.  I would never let anyone I love go that route– but there are a few narrow circumstances where it might make sense, which I detail in Debt Free For Life – if you are thinking about a debt settlement company make sure you check all your options and check them out with the Better Business Bureau.

Finally, there is Bankruptcy. Bankruptcies reached 1.5 million in 2010, the highest in five years.  With so many people who are drowning in debt and turning to bankruptcy I thought it was necessary to include a chapter explaining how it works, when to use it and how long it will take to recover. When it comes to bankruptcy, I always stress that you get professional financial and legal advice first, and to think of it as a temporary solution to a temporary problem – it doesn’t excuse you from making real changes in your life so you’re never in that situation again. But you need to know that filing bankruptcy is also not the end of your financial life. Let me stress—if you think that bankruptcy may be in your near future make sure that you don’t wait too long – act now and read Debt Free For Life!

BB: What further advice, that isn’t included in the book, would you give to a reader about to read the book?

David:

I would say if you are serious about getting out of debt and staying out of debt you should build a support team of your friends and family. Have them know what you are doing, see if they will join you in your pledge to a debt free life and use them as a support system. One of my favorite success stories is of a woman by the name of Genevieve – who has a “DOLP Team” at work that keep each other on track during their journey toward financial freedom – they pick each other up when they fall down, they work together and share their progress.

To provide further support for people on their journey toward financial freedom I encourage anyone in debt to join my Debt Free Challenge at debtfreechallenge.com. Challenge participants will be automatically entered to win $10,000 toward paying off their debts. Joining the challenge will help you commit to a debt-free life and stay motivated with free information and a community of support from others pledging to pay off their debts. Finally, you can join my Facebook community at www.facebook.com/davidbach – here you can share your accomplishments, ask questions, and speak to like minded individuals.

BB: What do you feel is the current state of personal finance?  (By that I mean, do you feel that people as a whole are moving in the right direction when it comes to their finances, or are we still stuck in a bit of a quagmire?)

David:

The truth is millions of Americans are buried in debt and want out! There is a movement in this country right now to pay down debt and save money. Savings rates are up to 6%, the highest in two decades, and debt levels are falling. One credit bureau estimates that more than 45 million people (or roughly one out of every five Americans with a credit score) want to improve their financial well being through debt reduction. Furthermore, according to creditcards.com almost $200 billion of credit card debt was paid off last year – so I think that people are starting to see the light about getting their personal finances under control – starting with paying off their debt.

People are ready to take action—smart action—that will help you become financially free and secure. And this is why I have written Debt Free For Life to give people new ideas and tools to help them be smarter about their money and their debt. The best system I’ve found for that is Debt Wise, which is an online tool that automatically pulls debt information from your Equifax credit report and uses it to create a priority debt payment plan while simultaneously tracking your progress towards debt freedom.  This online program basically does what I have taught for years as the “DOLP method” and does it automatically for you.  To get you started Equifax is offering a FREE trial of Debt Wise that so you can see how it will save you time and money while helping you pay down your debt.

I think that people have a lot of good intentions when it comes to their personal finances, but they still struggle with debt and don’t know how to start tackling it. Equifax, just released a report listing the top metro areas in the country hardest hit by credit card debt, and in many places, the percent of household income going to credit cards is more than 15 percent – and that doesn’t include car payments, mortgage payments, etc.  People are getting tired of the routine of going work, making money, spending money, going to work, making money, spending money. It’s time to free yourself from this vicious cycle by taking control of your finances.  I would encourage people to take a good, honest look at what their share of debt is and then make a plan of action for paying that debt down.

BB: Finally, what advice would you give to personal finance bloggers like myself?
David:

Be an advocate for your readers – they look to you for financial advice, so treat them as you would your best friend when dispensing advice. Act with integrity and don’t hesitate to tell the truth about personal finance topics, even ones that seem controversial. And always be responsible in how you present different subjects, being sure to fact-check and look at both sides of the issue first, but have an opinion. The more you care about your readers the more they will care about what you write and share.

I also just want to say thank you for taking the time to my book read and ask me these questions.  I really appreciate the support and the opportunity to help inform your readers!

My thanks to David for taking the time out of his very busy schedule to answer my questions. Again, I’ve got a review of the “Debt Free For Life” book coming up on Yakezie.com.  (I’ll link it when it goes live!) If you’d like to give the Equifax Debt Wise system a try (I’ll have a review coming up) I was able to secure a free trial for my readers.  If you go to http://www.debtwise.com/beatingbroke, you can sign up and give it a spin for free.  At the end of the free trial, you will be charged, so make sure that you cancel before the free trial expires!

Shane Ede

Shane Ede is a business teacher and personal finance blogger.  He holds dual Bachelors degrees in education and computer sciences, as well as a Masters Degree in educational technology.  Shane is passionate about personal finance, literacy and helping others master their money.  When he isn’t enjoying live music, Shane likes spending time with family, barbeque and meteorology.

beatingbroke.com

Filed Under: Debt Reduction, General Finance, Guru Advice, Personal Finance Education, pf books, Saving Tagged With: david bach, debt, debt free, debt free for life, dolp, interview, Saving

  • « Previous Page
  • 1
  • …
  • 56
  • 57
  • 58
  • 59
  • 60
  • …
  • 66
  • Next Page »

Improve Your Credit Score

Money Blogs

  • Budget and the Bees
  • Celebrating Financial Freedom
  • Christian PF
  • Clever Dude
  • Dual Income No Kids
  • Everybody Loves Your Money
  • Financial Panther
  • Gajizmo.com
  • Grocery Coupon Guide
  • Lazy Man and Money
  • Make Money Your Way
  • Money Talks News
  • Personal Profitability
  • PF Blogs
  • Reach Financial Independence
  • Saving Advice
  • The Savvy Scot
  • Yes, I am Cheap

Categories

Disclaimer

Please note that Beating Broke has financial relationships with some of the merchants mentioned here. Beating Broke may be compensated if consumers choose to utilize the links located throughout the content on this site and generate sales for the said merchant.

Visit Our Advertisers

Need to change careers? Consider an Accounting Certificate Program from WTI.
  • Home
  • About
  • We Recommend
  • Contact
  • Our Editorial Commitment

Subscribe to our newsletter

Please enable JavaScript in your browser to complete this form.
Loading


Beating Broke Personal Finance from the Broke Perspective

All content on Beating Broke is for entertainment purposes only. By reading this blog, you agree that Beating Broke is not responsible for any actions taken after reading this blog. For the full disclaimer.

Financial Disclaimer

Please note that Beating Broke has financial relationships with some of the merchants mentioned here. Beating Broke is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006-2026 Novara Unlimited LLC | All Rights Reserved. |
Privacy Policy | Terms of Service
Beating Broke is operated by Novara Unlimited LLC