Beating Broke

Personal Finance from the Broke Perspective

  • Home
  • About
  • We Recommend
  • Contact
  • Our Editorial Commitment

Powered by Genesis

How to Stop Overdraft Fees Before Holiday Swiping Starts

November 11, 2026 By Beating Broke Editorial Team Leave a Comment

A $6 pharmacy run should cost $6. If your debit card is opted into overdraft coverage, it can cost $43, and one 10-minute call to stop overdraft fees on your card fixes that before December gets here.

What one overdraft really costs

The CFPB found that some banks still charge overdraft fees as high as $37 each (CFPB Data Spotlight, April 2024). Walk that through on a $6 purchase: $37 divided by $6 is 6.17, so the fee is 617% of what you bought. Two of those a month is $74. Over a year, 2 x 12 x $37 is $888. For a lot of us, that’s more than what’s sitting in savings right now.

It stacks inside a single day, too. There’s no federal limit on how many overdraft fees you can be charged per day; the CFPB says some banks and credit unions set their own daily maximum, so you have to check yours.

Banks with more than $1 billion in assets reported $5.83 billion in overdraft and NSF (non-sufficient funds, the “bounced payment” fee) revenue in 2023, per the same CFPB report. That’s down 51% from $11.96 billion in 2019. Real progress, and still billions, much of it from people a few dollars short.

The protection that got repealed, and the one you still have

In December 2024, the CFPB finalized a rule to rein in overdraft fees at the largest banks. Congress voted it down, and the repeal was signed on May 9, 2025 (Public Law 119-10). No new federal cap is coming.

What you still have is older, and it works. Under Regulation E (the federal rule that covers debit cards and electronic transfers), a bank or credit union can’t charge you an overdraft fee on an ATM withdrawal or a one-time debit card purchase unless you opted in (12 CFR 1005.17(b)). You can take that consent back at any time, and the bank has to act on it “as soon as reasonably practicable” (12 CFR 1005.17(f)).

If you don’t remember opting in, you may have checked a box the day you opened the account. Your bank can tell you in one question.

How to stop overdraft fees in one call

  1. Find your number (5 minutes). Open your account’s fee schedule in the app or on the bank’s site. Write down the overdraft fee and the daily maximum. That’s the amount you’re protecting yourself from.
  2. Opt out of debit card and ATM overdraft coverage (5 minutes). Call the number on the back of your card, or look in the app’s settings. Say: “I’d like to opt out of overdraft coverage for ATM and everyday debit card transactions.” The rule says you can revoke consent the same way you gave it, so if you opted in online, look for the switch there first. After this, a purchase you can’t cover gets declined instead of costing you $37.
  3. Ask for the last fee back while you have them on the line. No law requires a refund. The fee is the bank’s policy, and so is waiving it. Try: “I was charged a $37 overdraft fee on [date]. I’ve opted out so it won’t happen again. Can you reverse that one?” If the answer is no, ask once more: “Is there someone who can review it?” Then let it go. Worst case, it cost you five minutes.
  4. Link a savings account as your backstop. A transfer from your own savings to cover a shortfall isn’t legally an overdraft service (12 CFR 1005.17(a)(2)), and the CFPB notes shortfalls can be covered by a transfer from a linked account. Fees for that transfer vary by bank, so ask what yours charges. Even $50 parked there can catch a short week. Skip the overdraft line of credit if they offer one; it’s a credit product (12 CFR 1005.17(a)(1)), which means you’re borrowing, with interest.
  5. Line up your autopays with payday (15 minutes). Opting out covers ATM and one-time debit purchases only. The CFPB confirms banks can still charge overdraft fees on checks and recurring electronic payments. Pull up your list of autopays (streaming, phone, car insurance) and check which ones land before payday. Move any you can to the day after your paycheck hits.

The catch

A decline at the register stings. If your card gets turned down with a line behind you, that moment is uncomfortable. It’s still $37 cheaper than the alternative, and a $20 bill tucked in your wallet for short weeks takes the edge off.

Opting out doesn’t cover everything. Recurring payments and checks can still overdraft, or bounce with an NSF fee that the CFPB says is often the same amount as an overdraft fee. A bounced autopay can also bring a late fee from whoever you were paying.

It doesn’t fix the gap. If you’re overdrafting every month, the real problem is the timing between your paycheck and your bills, and sometimes it’s plain not-enough. The switch stops the bleeding while you work on the budget.

If your bank keeps charging debit overdraft fees after you’ve opted out, or charged you when you never opted in, you can file a complaint with the CFPB.

What to do this week

Before your next payday, call the number on your card, opt out of debit and ATM overdraft coverage, and ask for your most recent fee back. Ten minutes on the phone, and the next short week costs you a declined card instead of $37.

Sources

  1. Consumer Financial Protection Bureau, “Data Spotlight: Overdraft/NSF revenue in 2023 down more than 50% versus pre-pandemic levels, saving consumers over $6 billion annually”, April 24, 2024 (accessed November 11, 2026)
  2. Electronic Code of Federal Regulations, 12 CFR 1005.17, “Requirements for overdraft services” (Regulation E) (accessed November 11, 2026)
  3. Congress.gov, Public Law 119-10, disapproving the CFPB rule “Overdraft Lending: Very Large Financial Institutions”, approved May 9, 2025 (accessed November 11, 2026)
  4. Consumer Financial Protection Bureau, “What can I do if my bank charged me a fee for overdrawing my account?”, last reviewed December 18, 2024 (accessed November 11, 2026)
  5. Consumer Financial Protection Bureau, “What is an overdraft?”, last reviewed January 31, 2024 (accessed November 11, 2026)
  6. Consumer Financial Protection Bureau, “How many overdrafts can I get in a single day?”, last reviewed January 31, 2024 (accessed November 11, 2026)

Filed Under: budget, Consumerism, Saving Tagged With: bank fees, overdraft opt out, stop overdraft fees

Save Money with Buy Nothing Groups

December 20, 2021 By MelissaB Leave a Comment

Save Money with Buy Nothing Groups

Have you joined a Buy Nothing group? You can find these groups on Facebook. Simply enter the name of your town or area and “Buy Nothing.” You likely find a group or two near you. Then, get ready to discover the joy of all the ways you can save money with buy nothing groups!

Save Money with Buy Nothing Groups

You save money in two ways:

Getting Rid of Your Stuff

You can easily get rid of stuff you no longer use with a buy nothing group. Take a picture and list your item in the group. You’ll likely have several takers. All you have to do is place said items outside your home, and the person will come to take them.

Using a buy nothing group to get rid of your stuff saves you gas because you don’t have to drop the items off at a donation center. You can also save on the cost of disposal if you want to get rid of a larger item.

Gaining New Stuff

The true beauty of these groups is when you are in need of items. Buy nothing groups never charge people for the items they’re getting rid of, so if you get an item from the group, you will pay nothing.

Some of the Best Items Our Family Has Received

When my son was in elementary school, he was obsessed with magic. Our local buy nothing group had a magic kit listed, and I got first dibs on it. My son was thrilled with his new-to-him magic kit, which was in excellent condition. About five years later, my daughters needed bicycles. Although it took me a few months, I was able to get both girls bicycles for free from our Buy Nothing group.

How to Make the Most of These Groups

How to Save Money with Buy Nothing Groups
Photo by Anna Kumpan on Unsplash

To make the most of these groups, you need to be flexible. You may want something, but you need to be patient. Sometimes you have to wait weeks or months for someone to list something you need. Also, be flexible with what you need. If you let go of rigidity, you may find what you need. For instance, let’s say you want blue plates. If someone offers up white plates, be flexible enough to take those instead, knowing that your need was met, even if it wasn’t in the exact way you had planned.

Another Bonus

Besides saving money with buy nothing groups, you also reap another benefit. You help keep unused items—either yours or someone else’s—out of landfills! You cut down on consumerism and live the motto of reduce, reuse, and recycle.

One Caveat

If you search for buy nothing groups in your area and don’t find anything, try searching under “freecycle” or “Neighbors helping neighbors.” Another option is to search “Free.” I found several groups in our area under these different terms. Hopefully, you’ll be able to find one.

Final Thoughts

If you haven’t heard of buy nothing groups or you haven’t utilized one before, what are you waiting for? Now is the perfect time to join. You’ll likely be pleased with the items that you need that you can get for free and that you can save money when giving your own items away.

Read More

What Christmas Expectations Are You Setting for Your Children?

6 Items You Should Never Pay Full Price For

How to Deal With a Person Who Keeps on Asking for Money

MelissaB
MelissaB

Melissa is a writer and virtual assistant. She earned her Master’s from Southern Illinois University, and her Bachelor’s in English from the University of Michigan. When she’s not working, you can find her homeschooling her kids, reading a good book, or cooking. She resides in New York, where she loves the natural beauty of the area.

www.momsplans.com/

Filed Under: Consumerism, Frugality, Saving Tagged With: buy nothing, Consumerism, freecycle, frugal

Are We Too Confident in the Stock Market?

August 22, 2018 By Shane Ede 4 Comments

Experts are fond of telling us all about the historic returns of the stock market. But, does our belief in that make us overconfident in the stock market?

You’ll have a hard time finding someone who won’t tell you that the market performs quite admirably over time.  It may have it’s ups and downs, but it performs at a rate that touches on double digits for longer periods of time.  And, it’s hard to argue with the facts.  Take the market for any given 10 or so year period and you aren’t likely to find too many periods where it hasn’t returned a pretty nice rate.  Especially when you compare it to the rates of savings accounts and CDs over the same period.

But, there’s  shady side to all of that.  Our confidence in the ability of the stock market to return those kinds of numbers can sometimes cause us to over-invest our portfolios.  Every time the stock market drops significantly (or crashes altogether) we hear stories about the person who was near retirement and now has to work for another 10 years because he/she lost it all in the stock market drop.  Invariably, you hear one of the reporters utter something about whether the stock market is as safe as we all make it out to be.

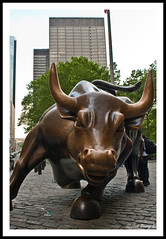
Charging BullAnd the truth is, no.  It’s nowhere near as safe as some would make it out to be.  In fact, it’s down-right risky.  And the less diversification you have, the riskier it becomes.  Hold all your money, or a significant portion of your portfolio, in one stock and you’re just as likely to suffer a tragic loss than you are to retire rich.  Ignore the more conservative professionals who suggest that you should move more and more of your money away from stocks and into something like bonds as you age, and you have a much higher chance of suffering a tragic loss.

Our confidence isn’t entirely misplaced, however. The facts remain that the market does return a healthy rate over time. Alongside traditional investments, exploring alternative investment strategies can also add value to your portfolio. While stocks and bonds play a crucial role, diversifying into different financial instruments ensures a balanced approach to investing, mitigating risks associated with market volatility. As long as you can weather a few down trends, you’re likely to come out on top if you just hold on for the ride. The overconfidence comes when you keep your money in too high of a percentage of stocks as you near retirement age. By the time you are 10-15 years from retirement (about age 50-55) you should have moved at least 50% of your portfolio away from stocks and into bonds. Your investment adviser should be able to help you with that, or you should sign up with a stock advisor service (like the Motley Fool Stock Advisor, or Betterment).  When you’re 5 or so years from retirement, you should be closer to 90% in bonds and other safer investments.  Yes, these investments are less likely to have high returns, but they also are almost guaranteed to return something.  And, as the old saying goes, something is better than nothing.

The bottom line is this.  Be aware of the risk of the stock market and that you should begin playing it safer as you near retirement age and you should be ok.  Don’t get overconfident in the history of the stock market and it’s giant returns.  Most importantly, find an investment adviser that you can trust and, at the very least, get their advice on your portfolio and it’s allocations, and you should find yourself hitting retirement with most of the money you expected to be there.

Image Credit: Charging Bull by kdinuraj, on Flickr

This post originally appeared on Beating Broke on 10/25/2010, and has been refreshed.

Shane Ede

Shane Ede is a business teacher and personal finance blogger.  He holds dual Bachelors degrees in education and computer sciences, as well as a Masters Degree in educational technology.  Shane is passionate about personal finance, literacy and helping others master their money.  When he isn’t enjoying live music, Shane likes spending time with family, barbeque and meteorology.

beatingbroke.com

Filed Under: Consumerism, economy, General Finance, Investing, Retirement, ShareMe Tagged With: bonds, bull market, Retirement, return, stock market, stocks

  • 1
  • 2
  • 3
  • …
  • 12
  • Next Page »

Improve Your Credit Score

Money Blogs

  • Budget and the Bees
  • Celebrating Financial Freedom
  • Christian PF
  • Clever Dude
  • Dual Income No Kids
  • Everybody Loves Your Money
  • Financial Panther
  • Gajizmo.com
  • Grocery Coupon Guide
  • Lazy Man and Money
  • Make Money Your Way
  • Money Talks News
  • Personal Profitability
  • PF Blogs
  • Reach Financial Independence
  • Saving Advice
  • The Savvy Scot
  • Yes, I am Cheap

Categories

Disclaimer

Please note that Beating Broke has financial relationships with some of the merchants mentioned here. Beating Broke may be compensated if consumers choose to utilize the links located throughout the content on this site and generate sales for the said merchant.

Visit Our Advertisers

Need to change careers? Consider an Accounting Certificate Program from WTI.
  • Home
  • About
  • We Recommend
  • Contact
  • Our Editorial Commitment

Subscribe to our newsletter

Please enable JavaScript in your browser to complete this form.
Loading


Beating Broke Personal Finance from the Broke Perspective

All content on Beating Broke is for entertainment purposes only. By reading this blog, you agree that Beating Broke is not responsible for any actions taken after reading this blog. For the full disclaimer.

Financial Disclaimer

Please note that Beating Broke has financial relationships with some of the merchants mentioned here. Beating Broke is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006-2026 Novara Unlimited LLC | All Rights Reserved. |
Privacy Policy | Terms of Service
Beating Broke is operated by Novara Unlimited LLC